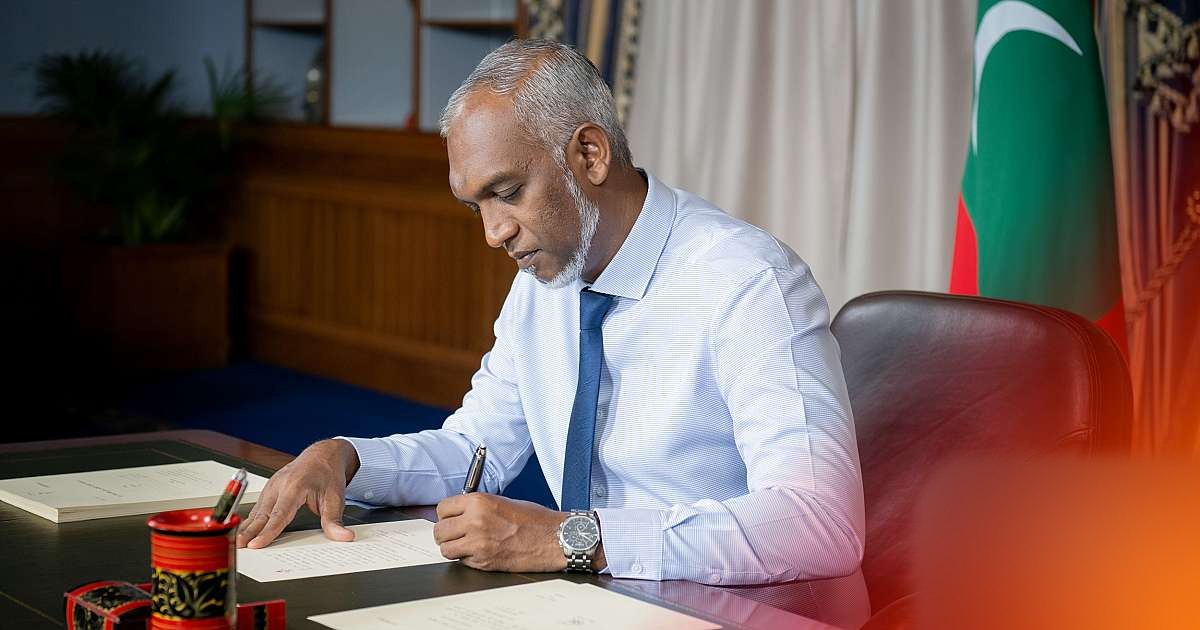
President Muizzu Ratifies Amendments Abolishing GST on Foreign Tour Operators
President Mohamed Muizzu today ratified amendments to three tax-related laws, abolishing the GST that had been collected from foreign tour operators since last October.
The amendments, passed by the People's Majlis in a vote last Tuesday, are the third amendment to the law on levying tax on income, the ninth amendment to the GST law, and the fifth amendment to the administrative law on levying tax.
Under the amendment to the law on levying tax on goods and services, the tax collected from tour operators and booking platforms is abolished from today. The tax, which began being collected last October, is being abolished to stop the collection of GST taken from the 1st of last month on inbound tourism products provided by parties that do not have a permanent business establishment in the Maldives, within tourism sector goods and services, and on agency or booking services provided in relation to such products. The amendment also removes provisions in the law relating to the collection of tax from booking platforms, travel agencies and tour operators. Businesses providing those services had expressed concern after the decision to bring an amendment to begin collecting the tax, and the amendment was brought and passed to address those concerns.
In addition, an amendment has been brought to increase the annual income threshold for mandatory GST registration from 1 million rufiyaa to 1.5 million rufiyaa, to take effect from the coming 1 January.
The amendment to the law on levying tax on income reduces the deductions that can be deducted from interest shown to other parties, excluding interest shown in relation to debt to a financial institution, in the calculation of income on which the tax of parties required to pay tax is based, and reduces the interest capacity tax-abated from 30 percent to 25 percent. This amendment will begin being applied from the coming January.
In the amendment to the administrative law on levying tax, the principle to be applied where a case can be appealed at the Tax Appeal Tribunal in relation to the amount of tax determined by the tax authority, MIRA, has been changed. Such cases can only be appealed after paying MIRA an amount equal to at least 50 percent of the amount being appealed. The situations in which this amount must be paid in full have been stated in the amendment, which also sets out how to act regarding any fine or interest that must be paid by the party paying tax in relation to the amount appealed at the tribunal. This amendment begins being applied from today.